Home Loan Guide for Apartments in Bangalore
Featured Image of Home Loan Guide for Apartments in Bangalore


A home loan for an apartment in Bangalore helps buyers purchase a home without paying the full property price at once. Buyers can pay a down payment and repay the remaining amount through monthly EMIs. The loan amount and interest rate depend on income, credit score, existing loans, and property value. Before taking a loan, it is important to compare banks, check home loan eligibility, plan the down payment, and check the property documents and RERA details. If you are planning to buy a project like Prestige Ivy Green, knowing the home loan process can help you plan your budget and make a better buying decision.
Key Highlights & Market Summary


Bangalore has many types of flats. You can buy budget homes or big gated flats. Bank approval depends on your salary and clean legal papers.

Financial Factor Standard Requirement (2026)
Bank Loan Share 75% to 90% of flat cost
Minimum CIBIL Score 750 or higher for low interest
Your Down Payment 10% to 25% of flat cost
Maximum Loan Time Up to 30 years
Must-Have Legal Clearances Karnataka RERA, A-Khata, BBMP Plan

Why Do Buyers Take a Home Loan in Bangalore?


Flats in Bangalore cost a lot of money today. Average flat prices run from ₹6,500 to ₹15,000 per square foot. Paying all the money at once can drain all your personal savings.

A loan helps you keep cash in hand. You need cash for extra costs like stamp duty, registration fees, interiors, and moving. Also, bank legal teams check the land papers for safety before giving you money.

How Much Home Loan Can You Get?


Banks check your monthly income to decide your loan limit. Most banks want your total monthly debt to stay under half of your net salary.

  • Net Monthly Income (100%): Your total monthly take-home salary.
  • Maximum Monthly Debt (50%): The limit for your new EMI plus existing card bills.
  • Living Cash (50%): Money left for food, bills, and family needs.

For example, a worker earning ₹1,50,000 net per month with no old debt can pay an EMI of ₹75,000 easily. This income helps you get a loan of about ₹80 Lakh to ₹95 Lakh for 20 years.

Home Loan Down Payment for an Apartment


Banks in India do not pay the full flat price. You must pay a part of the flat cost from your own pocket. This part is your down payment.

  • Bank Loan Share: 75% to 90% paid by the bank.
  • Your Down Payment: 10% to 25% paid by you.
  • Stamp Duty Tax: 5% of the flat cost paid to the state.
  • Registration Fee: 1% of the flat cost paid to the government.
  • Extra Costs: GST on new flats, lawyer fees, bank fees, and interior work.

If a flat costs ₹1 Crore and the bank funds 80%, the bank pays ₹80 Lakh. You must pay a ₹20 Lakh down payment. You also need about ₹6 Lakh extra for tax and registration.

Check Your Credit Score Before Applying


A CIBIL credit score of 750 or higher gets you cheap interest rates. Low scores can cause loan rejection or high interest rates.

  • Pay Bills Early: Pay all card bills and loan EMIs on time.
  • Use Cards Wisely: Keep your credit card usage below 30% of your total limit.
  • Avoid Too Many Loans: Do not apply for new personal loans right before a home loan.
  • Fix Errors Fast: Check your credit report to clear wrong entries quickly.

Compare Home Loan Interest Rates


Home loan rates are linked to RBI repo rates. Small rate differences save you a lot of money over 20 years.

  • Bank Spread: Check the extra interest percentage the bank adds to the RBI rate.
  • Processing Fee: Look for low file fees, usually under 0.50% of your loan.
  • Prepayment Fees: Pick floating loans with zero penalty for early loan payoff.
  • Speed: Select banks with fast legal teams to avoid purchase delays.

Choose the Right Loan Tenure


Your loan tenure affects your monthly EMI and total interest cost. Long loans mean low EMIs but higher interest over time.

  • 15-Year Loan: Higher monthly EMI, but you pay less total interest.
  • 30-Year Loan: Lower monthly EMI, but you pay much more total interest.

A ₹75 Lakh loan at 8.5% interest for 15 years has an EMI of ₹73,800. The total interest is ₹58 Lakh. Taking the same loan for 30 years drops the EMI to ₹57,600, but raises total interest to ₹1.32 Crore.

Documents Required for a Home Loan


Banks need basic personal papers and salary proofs to verify your profile.

For Salaried Workers

  • ID & Address Proof: PAN Card, Aadhaar Card, Passport, or Voter ID.
  • Income Papers: Last 3 months' salary slips and Form 16 for 2 years.
  • Bank Statements: Salary account statements for the last 6 months.
  • Work Proof: Office ID card and formal job letter.

For Self-Employed People

  • ID & Business Proof: PAN Card, Aadhaar Card, GST paper, and Business License.
  • Financial Papers: Audited P&L sheets and Balance sheets for 3 years.
  • Tax Papers: Income Tax Returns (ITR) for the last 3 years.
  • Bank Records: Business current account statements for 12 months.

Check the Apartment Documents Before Taking a Loan


Banks inspect property papers to ensure the building follows local city laws. Banks will reject loans for illegal flats.

  • Title Deed: Legal ownership papers for the last 30 years.
  • Commencement Certificate (CC): Building start permit from BBMP or BDA.
  • Occupancy Certificate (OC): Safety paper given to ready flats before moving in.
  • Khata Certificate: A-Khata document showing property details in city tax records.

RERA Check for Apartments in Bangalore


All new flat projects in Bangalore must register with Karnataka RERA (K-RERA). Banks only finance new flats that have valid RERA numbers.

Visit the official K-RERA website to check project end dates, builder details, and land safety approvals. Never buy a flat without a valid RERA registration number.

Home Loan Process for Buying an Apartment in Bangalore


Getting a home loan is simple when you follow clear steps.

  • Check Your Budget: Find your total savings and set a safe monthly EMI limit.
  • Apply for a Loan: Give your income slips and ID papers to get a sanction letter.
  • Property Check: Bank legal teams check land titles, BBMP plans, and RERA details.
  • Get Your Funds: Sign loan agreements, complete registration, and receive bank funds.

Can You Get a Home Loan for Under-Construction Apartments?


Yes, banks fund new building projects through stage-wise payments. The bank releases money to the builder as building work moves forward.

  • Stage 1: Foundation done (15% loan released)
  • Stage 2: 5th Floor slab done (20% loan released)
  • Stage 3: 10th Floor slab done (20% loan released)
  • Stage 4: Plaster work done (25% loan released)
  • Stage 5: Key handover (10% balance released)

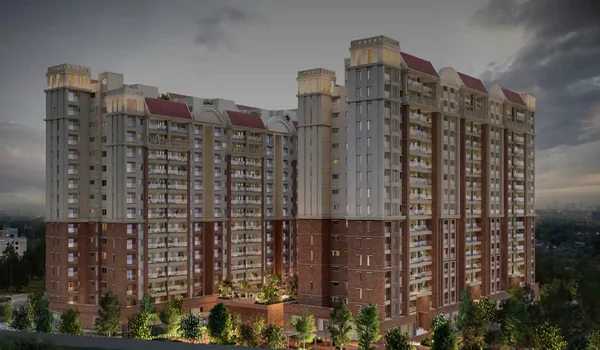
For example, buyers at Prestige Ivy League—a major flat project located about 17 km from Central Bangalore (MG Road) in HSR Layout—use stage-wise loans. Buyers can pay Pre-EMIs (only interest on released money) until they get key possession.

Home Loan EMI: What Should Buyers Consider?


Monthly EMI payments cover both interest and loan principal. Early EMIs cover mostly interest, while later EMIs clear your core loan.

Here, P is your loan amount, r is your monthly interest rate, and n is your total loan months. Keep total monthly EMIs under 40% of your take-home pay.

Fixed vs Floating Home Loan Interest Rate

You can pick fixed or floating rates based on your financial plan.

  • Fixed Interest Rates: Your interest rate stays the same every month. It makes monthly planning easy, but starting rates are higher.
  • Floating Interest Rates: Your rate changes when the RBI changes bank rates. Starting rates are lower, and you pay zero early payoff fees.

Should You Take a Joint Home Loan?


A joint loan lets family members combine income to get a bigger loan amount. You can apply with your spouse, parent, or child.

  • Higher Sanction: Combining two incomes helps you get a larger bank loan.
  • Tax Savings: Both co-borrowers can claim separate tax cuts if both own the property.

Tax Benefits on Home Loans

You can save tax money on home loan repayments under Indian tax laws.

  • Section 24(b): Save up to ₹2,00,000 per year on home loan interest paid.
  • Section 80C: Save up to ₹1,50,000 per year on principal repayments and registration fees.
  • Joint Benefits: Both co-owners get full individual tax deduction limits.

Common Home Loan Mistakes to Avoid

Avoid these simple financial mistakes when taking a home loan:

  • Borrowing Too Much: Do not take the maximum loan offered by the bank.
  • Ignoring Extra Fees: Always budget cash for stamp duty, registration, and interiors.
  • Skipping Legal Checks: Check BBMP permits and RERA details yourself.
  • Using All Savings: Keep emergency cash in your bank for hard times.

How to Make Your Home Loan Easier to Manage

Manage your loan well to clear debt faster and save money.

  • Pay Extra Early: Put annual bonuses into your loan to cut down on your main debt fast.
  • Raise EMI Yearly: Increase your monthly EMI by 5% every year as your pay grows.
  • Watch Rate Changes: Ensure your bank passes on RBI interest rate cuts to you.
  • Keep Emergency Cash: Save 6 months of EMI money in a secure bank account.

Home Loan Checklist for Apartment Buyers in Bangalore


Use this short checklist before booking your flat:

Pre-Application Planning

  • Fix your total flat budget, including tax and registration.
  • Check your credit score to make sure it is over 750.
  • Calculate a safe monthly EMI for your household budget.
  • Save 6 months of emergency living cash.

Legal & Document Checks

  • Verify project K-RERA number on the official site.
  • Check BBMP plans and confirm A-Khata status.
  • Gather salary slips, tax papers, and bank statements.
  • Compare bank rates and processing charges.

Final Thoughts


Getting a home loan in Bangalore is simple when you plan your budget and check legal papers early. Check your monthly income, improve your credit score, and keep your tax papers ready. Compare loan rates across multiple banks to secure the best deal.

Always verify builder land titles, A-Khata papers, and K-RERA details before paying booking cash. Whether buying in central areas or choosing projects like Prestige Ivy League (located about 17 km from Central Bangalore), smart planning makes home buying stress-free.

FAQs


1. How much home loan can I get for an apartment in Bangalore?

Banks pay 75% to 90% of the flat price. The final loan amount depends on your salary, credit score, and clean land papers.

2. What minimum CIBIL score is needed for home loan approval?

A score of 700 works, but a score of 750 or higher gets you the lowest interest rates and fast approval.

3. Can I get a home loan for an under-construction apartment?

Yes. Banks grant loans for under-construction flats registered under Karnataka RERA. The bank pays the builder in clear stages as work progresses.

4. Do banks check property papers before giving a loan?

Yes. Banks send legal experts to verify land papers, city permits, and site safety before releasing loan money.

5. What key documents are needed for a home loan?

You need your PAN card, Aadhaar card, salary slips, Form 16, bank statements, Sale Agreement, BBMP permits, and K-RERA numbers.

Enquiry
Enquire Now